A 20-year-old Utah driver says his monthly car insurance payment jumped from $178 to $238 despite having no accidents or claims on his record. The nearly 34% increase prompted an angry Reddit post about rising living expenses and how difficult it has become for young drivers to get ahead financially.
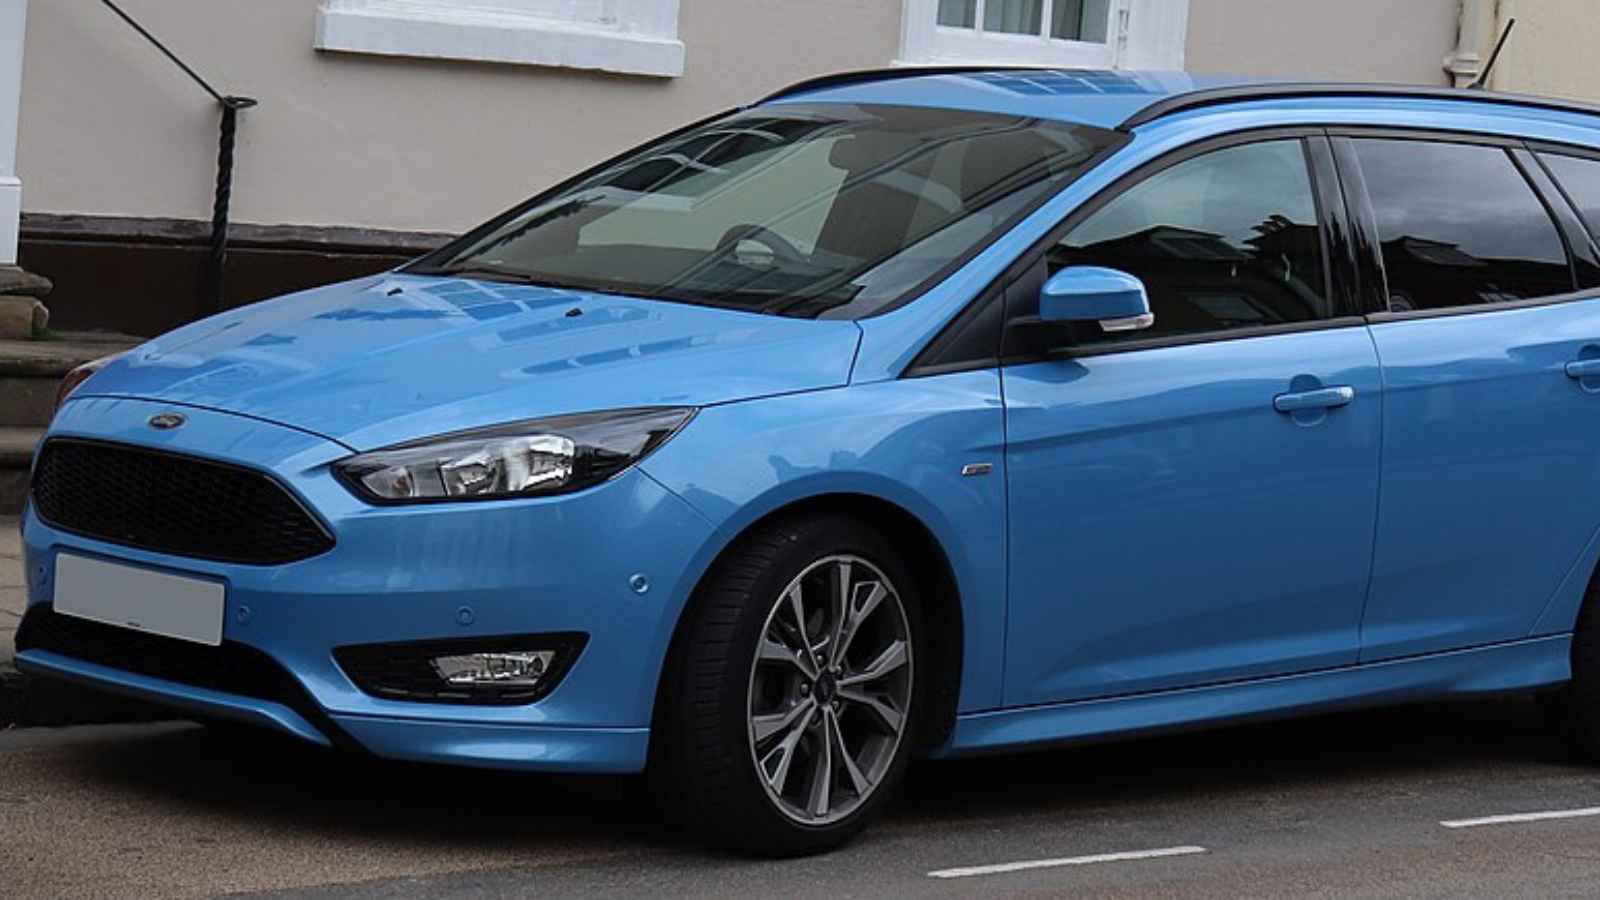
The driver owns a 2017 Ford Focus ST, which he purchased about eight months earlier with a $9,800 loan. Because he financed the vehicle, his lender requires full coverage insurance. He had been paying approximately $178 a month through GEICO before discovering the increase.
Working 50 to 60 hours a week in construction, the driver says he earns approximately $70,000 annually and hopes to purchase a house next year. But with housing, groceries, fuel, and other expenses eating into his income, the unexpected insurance increase has complicated his financial plans.
His frustration quickly drew attention in Utah’s Reddit community, where other drivers shared similar experiences and suggested shopping for coverage elsewhere instead of accepting the higher payment.
Unexpected Insurance Hike
My auto insurance went from $178 to $238 (+34%) and I’m pissed
by
u/Open-Elk-2757 in
Utah
In his r/Utah post, the driver explained that he had budgeted about $180 for his insurance payment when he opened the GEICO app and saw the new $238 charge.
He immediately called the insurer to ask why his premium had increased.
According to his account, a GEICO representative attributed the increase to higher repair costs and rate changes requested in Utah. The representative reportedly explained that vehicle repairs have become significantly more expensive.
The driver’s additional $60 monthly expense amounts to $720 annually if the higher rate remains in effect for 12 months.
He also expressed anger toward Utah insurance regulators, whom he blamed for allowing rate increases. However, his account does not establish which specific rate filing affected his policy or whether other changes contributed to the higher premium.
Drivers React
The discussion quickly shifted toward ways the driver might reduce his expenses. Several commenters recommended getting quotes from competing insurers, with some claiming they saved hundreds of dollars by switching companies.
Others pointed to the driver’s age and vehicle choice. A 20-year-old driving a Ford Focus ST, a performance-oriented hatchback, may face different insurance rates than an older driver operating a less sporty vehicle.
One commenter reported cutting an insurance payment in half by switching providers. Another explained that a speeding ticket and a previous accident made it much harder to find affordable alternative coverage.
The responses highlighted how dramatically premiums can vary depending on individual circumstances, driving history, and the insurer.
What Affects Rates?
The Utah Insurance Department explains that car insurance premiums depend on multiple factors, including driving history, age, location, vehicle type, and coverage.
Insurers also evaluate the financial risk of providing coverage, so a driver may see a premium increase without personally causing an accident or filing a claim.
The department recommends comparing quotes from different companies using matching coverage limits and policy details. It also encourages drivers to ask about available discounts.
For the Utah driver, switching insurers may reduce his expenses, though no company guarantees a lower rate.
The Reddit post did not include documentation explaining how GEICO calculated the increase. The driver also had not reported finding a cheaper replacement policy in the original post.