A customer walked into an Ontario luxury car dealership hoping to drive away in an $85,000 Porsche Panamera. With a strong credit score and money for a deposit, the purchase seemed possible until the dealership began checking his finances.
Staff at Toronto Auto Brokers noticed several unusual details in his credit file. Despite having a score of 770, the buyer had applied for credit with numerous banks in a short period. He also arrived without his driver’s license.
The dealership still wanted to make the sale. After all, the customer had an established credit history and was willing to put $5,000 down on the Porsche. However, one bank had already turned him down while he was shopping for a Chevrolet Camaro.
As employees looked deeper into the application, another credit report revealed a $90,000 vehicle loan the customer said he knew nothing about. What began as a routine car sale soon became a question of whether the dealership could trust the information it had received.
A Strange Discovery
Embedded media follows; please allow a moment to load.
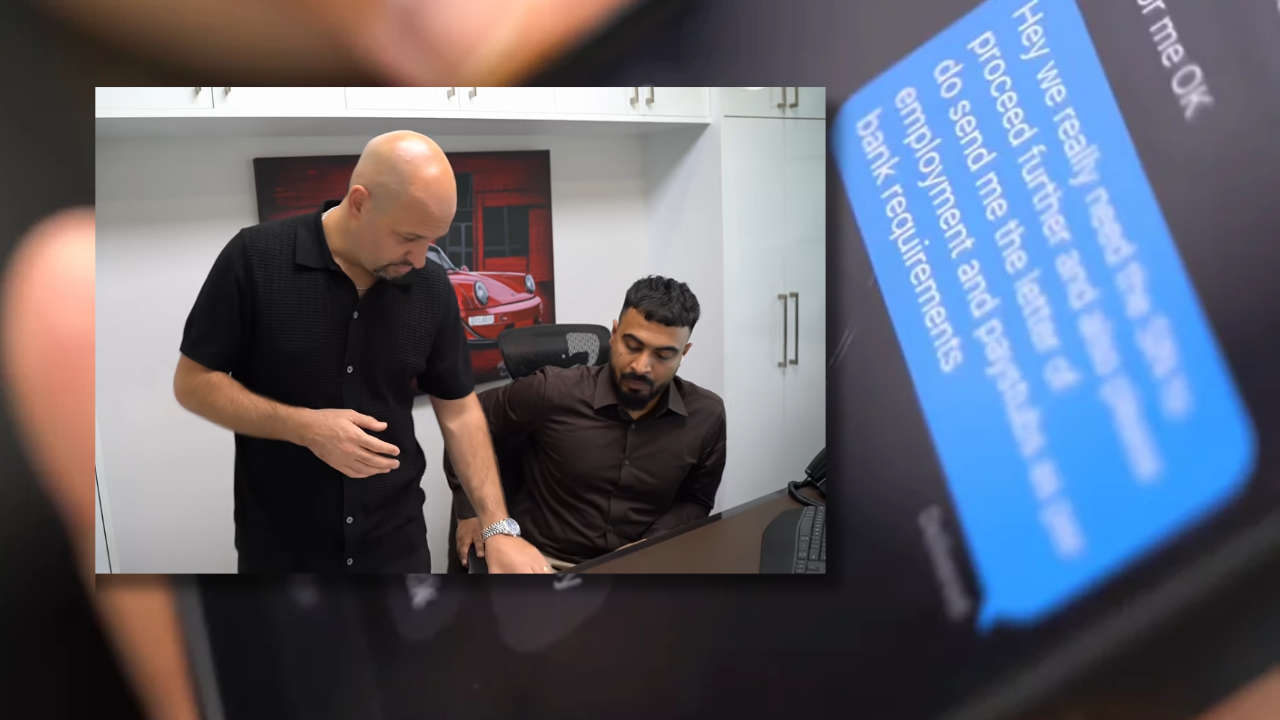
In a video shared by Toronto Auto Brokers, a manager reviews the application with salesperson Kamal. The buyer’s credit score looks promising, but the manager counts 12 recent inquiries from different banks.
Another detail offers some reassurance. The customer has an existing car loan with about $12,000 remaining, down from an original balance of roughly $42,000. That suggests he has been making payments on a vehicle for years.
Still, the dealership wants to be careful. When the buyer returns, Kamal checks his driver’s license with an electronic verification system. The document passes, allowing the customer to take the Porsche for a test drive.
While the car is out, the manager submits the financing application. The bank declines it, and a phone call reveals something neither employee expected.
Another $90,000?
According to the manager, the lender found another $90,000 auto loan on the customer’s TransUnion credit report. That debt had not appeared on the Equifax report the dealership reviewed earlier.
The bank also raises the possibility of a mixed credit file because the customer has a common name. It asks for his Social Insurance Number, or SIN, to help confirm which records belong to him.
When Kamal speaks with the buyer, he denies having the larger loan. He does confirm opening two new credit cards, another detail the lender mentioned.
Financing also presents a separate problem. The bank wants at least $10,000 down, but the customer says $5,000 is his limit. Without more money and the requested information, approval remains out of reach.
Running Out Of Answers
The next day, Kamal updates the manager. The customer still has not supplied his SIN, telling the salesperson he cannot find it. Yet he continues asking when he can collect the Porsche.
Concerned by the conflicting information, the manager consults his father, Steven, who advises him to return the deposit rather than continue with a deal he considers suspicious.
The manager also asks Kamal to request proof of employment. Before the dealership can move forward, however, the customer sends a message asking for his deposit back.
Kamal says the buyer has also stopped answering his calls.
The Deal Is Off
By this point, the manager believes the attempted purchase may have involved financing fraud. He suspects the customer could have been seeking multiple large loans before leaving lenders unpaid.
That remains the dealership’s suspicion, not an established finding. The video does not confirm whether the $90,000 loan belonged to the buyer or resulted from a credit-report mix-up.
With no financing approval and the buyer requesting his money, the dealership agrees to refund the $5,000 deposit.
The Vaughan-based dealership ultimately keeps the Porsche rather than completing the sale. The manager ends the video frustrated by the time spent reviewing the application, while Kamal is instructed to return the customer’s money.