If you’ve been in the market for a new car in the past few years, chances are you’ve seen how much more expensive today’s vehicles have gotten. The prices increased around the same time the world was experiencing COVID-related lockdowns, and they haven’t really gone back down since.
That has changed the car-buying landscape, altering the way many people look at the process of buying a new vehicle, from the types of automobiles they are choosing to how they’re paying for them.
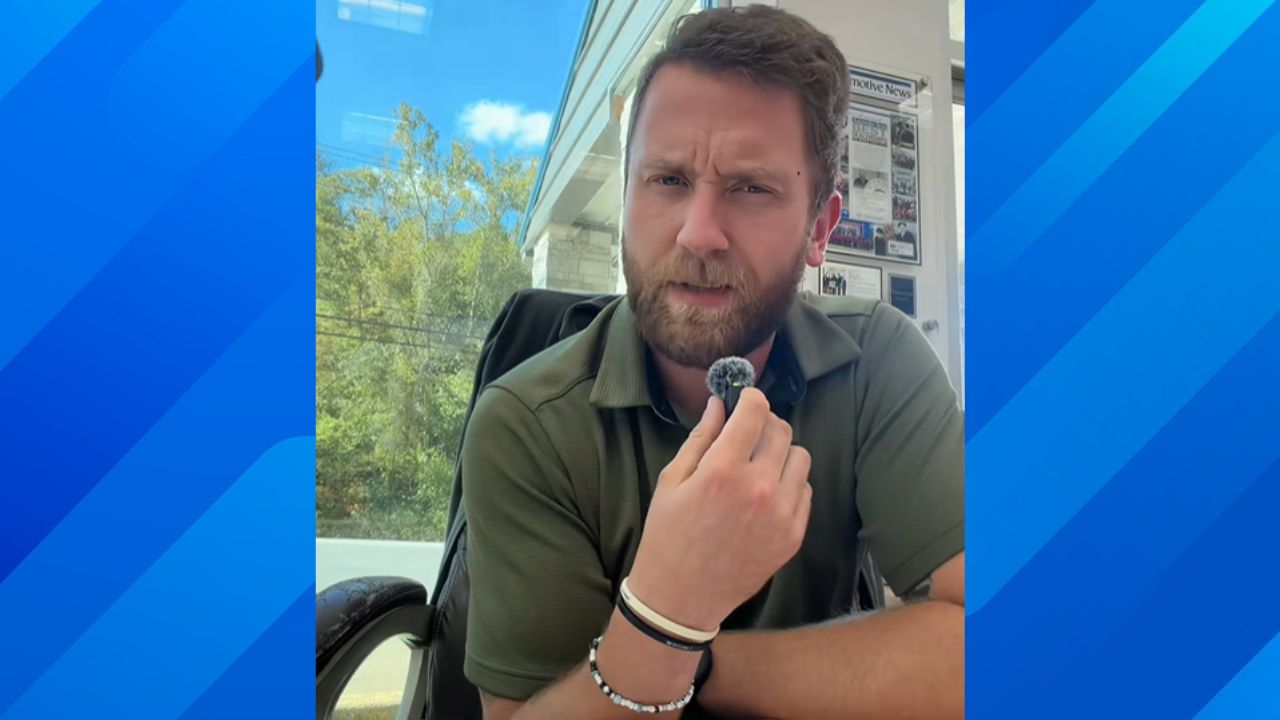
According to one auto dealer on TikTok, that means embracing new financial options, like an 84-month car loan. Now, @SpittinBarsSellinCars is explaining why so many are opting for the longer term, and how people can actually make it work to their advantage.
Of course, there are definitely those who disagree with his advice, especially those who say that the financing option isn’t lining up with the reality of modern vehicles, which may not last through the life of the loan.
TikToker Says 84-Month Car Loans Are Becoming the Norm
@spittinbarssellincars The only correct way to do an 84-month term on a vehicle loan! This, of course, isn’t financial advice; it’s just the way I’ve always done it, and it turns out well for me 😂 #carsales #behindthescenes #carshopping #carsalesman ♬ original sound – SpittinBarsSellinCars.
The auto loan has changed a lot over the years, and there was a time when auto loans were usually paid off in 36 to 48 months. But increased prices led to longer loan terms, giving car buyers the option to spread the cost of a new car over a longer period, lowering the payment.
Today, it’s not uncommon to see loan terms as long as 84 months (seven years). In fact, @SpittinBarsSellinCars says that he is seeing more of these types of loans than others these days. “Cars are like, 90 grand now,” he explained in his video, noting that those were the higher-end models. “As cars get more expensive, then extended loan terms to afford them become expected.”
There Are Ways to Take Advantage of Longer Loan Terms
While he argues that these terms are a necessity for some, they could turn out to be a real lifesaver for those who don’t need to lower their payments. The TikToker says someone who can afford a higher car payment should still consider taking out the longer loan term to lessen their payment so that they have some wiggle room in the event of an emergency.
He uses the example of a $900 monthly payment on a 48-month loan versus a $500 monthly payment on an 84-month loan, saying that if you can afford the payment at 48 months, you should consider stretching it over 84 months while paying more than you owe each month. That way you’re still paying down the loan as you go (and saving money on interest by paying it off early) while also giving yourself some breathing room in the event that there’s an emergency and that $900 a month payment suddenly becomes unaffordable.
People Didn’t Agree with His Logic in the Comments
When @SpittinBarsSellinCars first started his video explainer, he did mention that there would be people who disagreed with his advice. As it turns out, he was not wrong. The comments were full of folks who thought that he was just trying to convince people to overextend themselves in order to make a sale.
“That’s definitely a salesman’s point of view,” one person wrote.
Then some said that the 84-month car loan was a bad idea for an entirely different reason. “A lot of vehicles won’t make it 84 months,” they wrote.
“This makes sense. But to be fair, if 84 months is going to be some version of a new normal, these car manufacturers need to be held to a standard that their cars will last 84 months,” another person added.
Whether @SpittinBarsSellinCars’ advice is sound or not will likely boil down to an individual’s specific financial situation. That being said, if the comments are any indication, most people don’t seem to like the idea that an 84-month car loan is becoming the new normal in the world of auto financing.